

“Over the years we’ve invested significantly in our field data team - focusing on producing trusted ratings. While this ensures the accuracy of our Ratings, it doesn’t allow the scale across the thousands of projects that buyers are considering.”

For more information on carbon credit procurement trends, read our "Key Takeaways for 2025" article. We share five, data-backed tips to improve your procurement strategy.
One more thing: Connect to Supply customers also get access to the rest of Sylvera's tools. That means you can easily see project ratings and evaluate an individual project's strengths, procure quality carbon credits, and even monitor project activity (particularly if you’ve invested at the pre-issuance stage.)
Book a free demo of Sylvera to see our platform's procurement and reporting features in action.
What Is a Marginal Abatement Cost Curve?
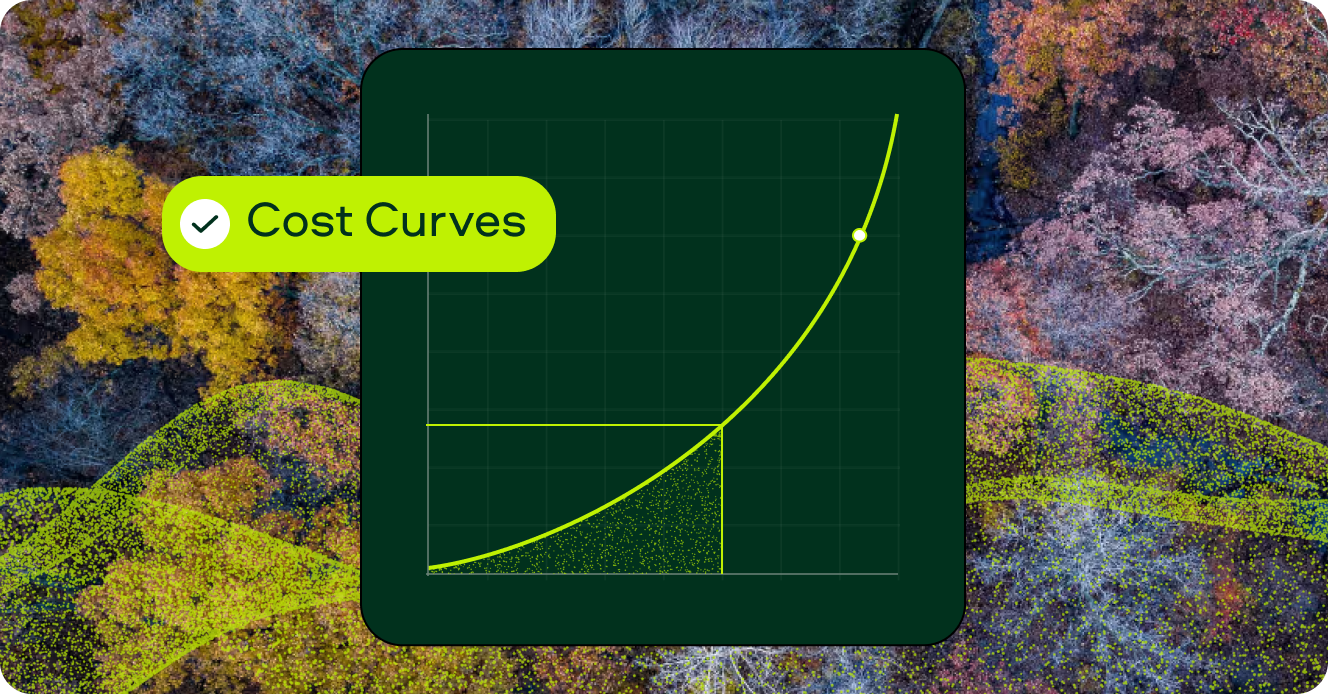
A marginal abatement cost curve (MACC) is a graph that ranks emission reduction options based on both expense and reduction potential. Each bar on the graph represents one option.
Digging deeper, the height of each bar represents the marginal abatement cost, i.e., the cost to abate one more unit of greenhouse gas emissions, which is usually a tonne of CO2e. Its width, on the other hand, represents how many tonnes that specific option can deliver.
The horizontal axis accumulates abatement from left to right, showing the total emissions reductions you achieve across options. So, if you draw a vertical line at your target, everything to the left belongs in the plan. The abatement curve shows the most cost-effective ways to hit the target.
Bars below the axis represent negative-cost options that generate more savings than they cost. Common examples include energy-efficient lighting and heat recovery.
Government bodies use MACCs to shape energy policy. The World Bank’s MACTool, for instance, helps policymakers compare the costs and benefits of emission reduction options and assess the investment that a national economy needs to make for low-carbon development. The same logic now applies to corporate budgets in manufacturing, transportation, and other sectors.
Why a MACC Beats a Simple Price Comparison
A price list tells you that durable removals cost more than efficiency measures. Everyone already knows that, so a price list won’t give you actionable advice or change your budget.
A MACC adds a dimension that price lists ignore: volume. For a company with a 50,000-tonne gap, an option at $5 per tonne that delivers only 200 tonnes barely registers. An option at $40 per tonne that covers all 50,000 tonnes is worth far more, despite its higher marginal cost. In other words, the width of the bars on a MACC is incredibly valuable information.
This is especially true when it comes to carbon procurement, because the cheapest levers almost always face the tightest volume limits. Efficiency projects, for example, cap out at the energy you actually use. High-quality credit supply runs short, too. In our State of Carbon Credits 2025 report, we found that BBB+ credits were in deficit for a third consecutive year. As a result, plans that sort by price alone can run out of cheap options long before they reach their targets.
How to Build a MACC for Carbon Procurement
To build a MACC for carbon procurement, follow these three steps: define the boundary and target, inventory and cost every option, and size each one honestly.

Define the Boundary and Target
Decide which carbon emissions sit inside the curve, over what timeframe, and against which baseline. A curve for a 2030 interim target will look very different than one for 2050.
Then decide what you’re solving for, as gross reduction, a net position, and the tonnes that a specific framework will recognize each produce different curves.
The SBTi Corporate Net-Zero Standard V2, for example, sets rules that define what counts toward a target. That information will help you decide which bars belong on the curve.
Inventory and Cost Each Option
List every lever that you can realistically pull. Typical options include:
- Internal Measures: Heat pumps, electric vehicles for transport, and wind/solar/renewable energy
- Physical Low-Carbon Procurement: Lower-carbon steel, cement, and fuels
- Attribute Certificates: Particularly ones that carry a verified environmental claim
- Carbon Credits: Specifically credits at each quality rating band
- Carbon Removals: From nature-based sequestration to durable engineered storage
It’s important to remember that cost per tonne differs from the sticker price.
For internal measures, add annualized capital to the change in operating cost, then divide by annual abatement. A heat pump that lowers total energy costs can land below zero.
For physical commodities, divide the premium over the conventional alternative by the difference in embodied carbon. Only add the incremental costs to the calculation, not the full product price.
In regard to physical commodities, a common mistake is comparing green steel premiums to credit prices. But this is only a valid comparison if both are expressed per tonne of CO2e, which requires the verified carbon intensity difference.
A hypothetical $40 premium per tonne of steel costs $40 per tonne abated at a 1.0 tCO2e intensity difference, but $80 at 0.5 tCO2e. Sylvera’s Commodity Insights covers facility-level carbon intensity across 3,000+ cement and 700+ ammonia facilities, which gives the denominator a verified basis.
Finally, include the cost of evidence. Verification, assurance, and documentation cost money in the real world, but the amount you spend depends on the lever you pull.
Size Each Option Honestly
Make sure the width on the graph reflects the volume you can contract. A removal pathway with a million tonnes of global capacity is only a million-tonne option if you can secure all of the supply.
Add a time dimension, too. Some options are available now, while others depend on implementation timelines that run three years or more. A curve without timing implies you can buy everything today, which is rarely the case. MACCs with timing are more accurate.
Where Marginal Abatement Cost Curves Mislead
Because MACCs measure cost at the margin, they suit modest cuts better than deep decarbonization, per the World Bank. Here are four ways the tool can mislead you if you’re not careful:

- It treats a moving market as a still photograph: Credit prices move, removal costs fall, green premiums narrow as low-carbon production scales, and carbon pricing raises the cost of pollution, and therefore the cost of doing nothing. The options most likely to reprice sit among the highest cost bars on the right, exactly where the marginal decision sits. So, build with forward price views instead of spot ones, and rebuild on an annual basis, at the very least.
- It assumes options act independently: Electrifying a process changes the value of buying low-carbon fuel for it. In addition, securing physical low-carbon supply shrinks the residual that removals must cover. Where interactions run strong, the sum of the bars overstates achievable abatement, leading to “solid” plans but missed targets.
- It prices what’s easy to price: Options with clean cost data make it onto the curve, but those with messy data tend to drop off – or they’re given a placeholder that determines the answer. That bias works against newer levers, right where the strategic opportunity runs largest.
- It hides the negative-cost paradox: If measures below the axis paid for themselves, the obvious question is why nobody has done them. Usually, the model has omitted a real restraint, such as capital rationing, disruption, limited internal resources, or the payback thresholds finance teams apply to new investments. Treat large negative bars as a prompt to interrogate the model, and confirm costs before implementation.
All four issues are rooted in data. A curve that rests on verified prices, real availability, and forward views works as a decision tool. A curve that rests on assumptions is just a guess.
What a Good Curve Requires
To fix the issues above and build an effective MACC, you need five inputs.
- Prices that span the levers: Every option needs a price on a consistent per-tonne basis. A curve that mixes cost per unit of product with cost per tonne of CO2e ranks numbers that don’t share a unit. This makes the curve practically worthless.
- Quality-adjusted credit pricing: Credits don’t behave as one option because price varies – sometimes significantly – by rating band, as our analysis of the carbon credit quality and value gap shows. An undifferentiated average misprices much of the plan.
- Verified carbon intensity for physical options: A green premium, for example, is only meaningful if it’s compared to a verified intensity difference. This fact makes independent assessment essential. Unfortunately, the spread is wide. At Sylvera, we found cement carbon intensities ranging from 0.03 to 1.24 tCO2e per tonne across 3,000+ facilities.
- Forward views rather than spot: A carbon procurement plan commits spending across several years, so the price data should cover the same timeframe. After all, spot prices go stale fast. ARR credits rated BBB or above started 2025 at roughly the same price as lower-rated equivalents but averaged more than $26 by late 2025, compared to $14 premium for lower-quality supply. Put simply, curves built on January spot prices weren’t accurate for very long.
- Availability data alongside price: Volume makes up half the curve, and it’s the half most teams estimate. Reliable availability data shows what you can actually contract, and when.
Build Your Cost Curve on Real Market Data
Sylvera offers independent data across the curve to help you make better investment decisions.

- Pricing across the levers: Sylvera’s Market Intelligence covers credit and removal pricing, with 20,000+ spot price estimates that draw on 300,000+ transactions across eight price indices. Each estimate carries a low, mid, or high confidence band, so your model knows how solid each input is. Then, Commodity Insights adds verified carbon intensity for the physical lever.
- Quality-adjusted pricing: Sylvera’s Ratings data shows buyers paying roughly $5 more per rating band for ARR and around $2 per band for REDD+, with A-rated ARR projects averaging about $40 per tonne, against roughly $11 for a B-rated one. High-quality credits (BB+ and above) also account for around 50% of retirements but roughly 70% of spend. Segmenting by quality is what separates a plan that survives due diligence from one that doesn’t.
- Forward curves for a multi-year decision: With Sylvera, price projections run to 2050 under low, mid, and high scenarios by project type and market. And they’re refreshed quarterly with published methodology notes. Because of this, you can build a curve for the year your target lands instead of the year you drew it, which keeps the curve relevant to the decision.
- Availability alongside price: Sylvera’s Market Gateway gives buyers access to more than 400 million tonnes of listed inventory, which supports the volume side of the curve.
- Independence: Sylvera doesn’t hold inventory, take market positions, or take a cut of transactions. As such, we don’t let commercial incentives shape the data in your model.
Want to learn more about how Sylvera can help you make better investment decisions? Request a demo to build a cost-per-tonne comparison based on current data.